Tax-loss harvesting is a year-round recordkeeping and investment decision, not a December race. A loss on the screen is not yet a deductible loss, and a carried loss is not a savings account from which you choose withdrawals.
Before you get started, we’d recommend reading through Gain-offset planning, Tax alpha: the model and its limitations, Concentrated stock and RSUs, Roth conversions and tax-loss harvesting.
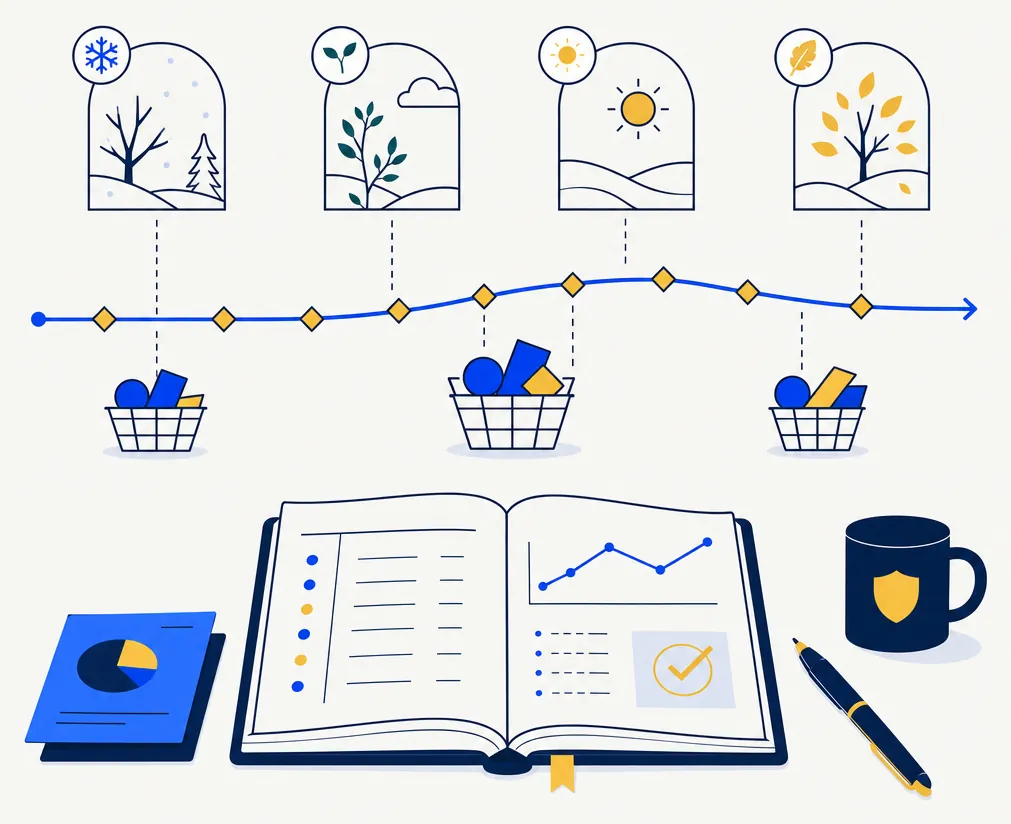
What does pacing mean?
How should a beginner pace tax-loss harvesting?
Review positions and records throughout the year. Before any loss sale, check recent purchases and planned replacements across relevant accounts. At tax time, apply the annual netting and carryover rules; a larger loss balance is not automatically a better investment result.
There is no universal best month or required number of harvests. Transaction costs, the replacement investment, holding periods and your own circumstances matter. Selling solely to build a loss balance can change an investment you still want to own.
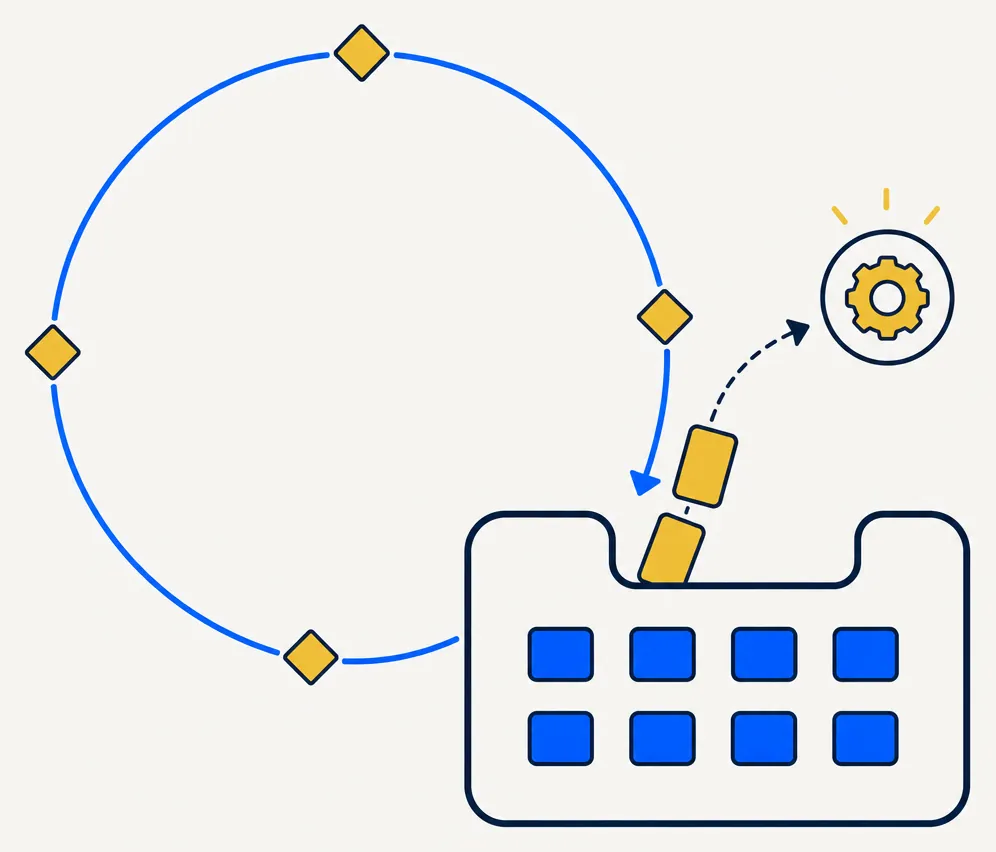
A realized loss has an annual order
What if there are no capital gains to offset?
After annual capital-gain netting, a net capital loss may offset ordinary income up to $3,000, or $1,500 for married filing separately. The unused amount may carry forward under the IRS worksheet rules.
The allowable current-year deduction affects the carryover even if you do not claim it. You cannot preserve it for a preferred future year simply by leaving it off your return. The $3,000 limit applies to single and married-filing-jointly returns; the $1,500 limit applies to married filing separately.
An illustrative calendar, not a trading schedule
What can I review at different points in the year?
Early in the year, reconcile prior returns and carryovers. During the year, monitor acquisitions, realized activity and portfolio changes. Before year-end, review the complete records rather than rushing a sale to meet an arbitrary loss target.
The calendar below is an organizational example. It does not recommend a trade or promise that losses will be available. A December sale can have a January wash-sale purchase within its forward window.
Investment decisions still come first
Should I sell appreciated investments just to use a carryforward?
Not automatically. A carryforward is one input when considering a sale you otherwise have a reason to make, such as a change in allocation or a cash need. It is not a reason by itself to realize gains.
Annual tax rules determine the application of losses. Your investment choices and tax filing are related, but they are not interchangeable. Harvesting often defers tax rather than eliminating it.
The common mistake: incomplete records
What should I avoid when tracking a loss balance?
Do not mistake a running total of harvested losses for the carryover on your filed return. Gains, deductions, wash-sale adjustments and the short-term or long-term character of losses affect the amount carried to the next year.
Keep broker records and your tax return together. Reconcile the next year’s opening balance to the applicable carryover worksheet, including income-related adjustments. The figures below illustrate recordkeeping, not elective use of a reserve.
A useful review checklist
What belongs in a year-round review?
Review realized gains and losses, the filed carryover, purchases in the wash-sale window, planned replacements and missing account information. Review purchases before selling, not only after a loss has been realized.
Dividend reinvestments and purchases in a spouse’s account or your own IRA can matter. A product can only work with the accounts and information available to it; unconnected accounts still need a separate review.
Continue learning
What should I read next?
Start with the mechanics of harvesting, then learn the carryforward and wash-sale rules before considering a tax-motivated sale.
A repeatable review is useful; a promise of a particular tax benefit is not. This article describes a process, not a performance outcome.
Sources and further reading
Where can I check these rules?
Use the applicable IRS guidance and your tax-return instructions.
Primary sources checked October 11, 2026: IRS Publication 550 (2025), capital losses and wash sales; IRS Topic 409; Revenue Ruling 2008-5 (own IRA/Roth IRA case). These sources address different rules, not one blanket household ruling.
Explore paper practice (invitation required) — join the paper waitlist